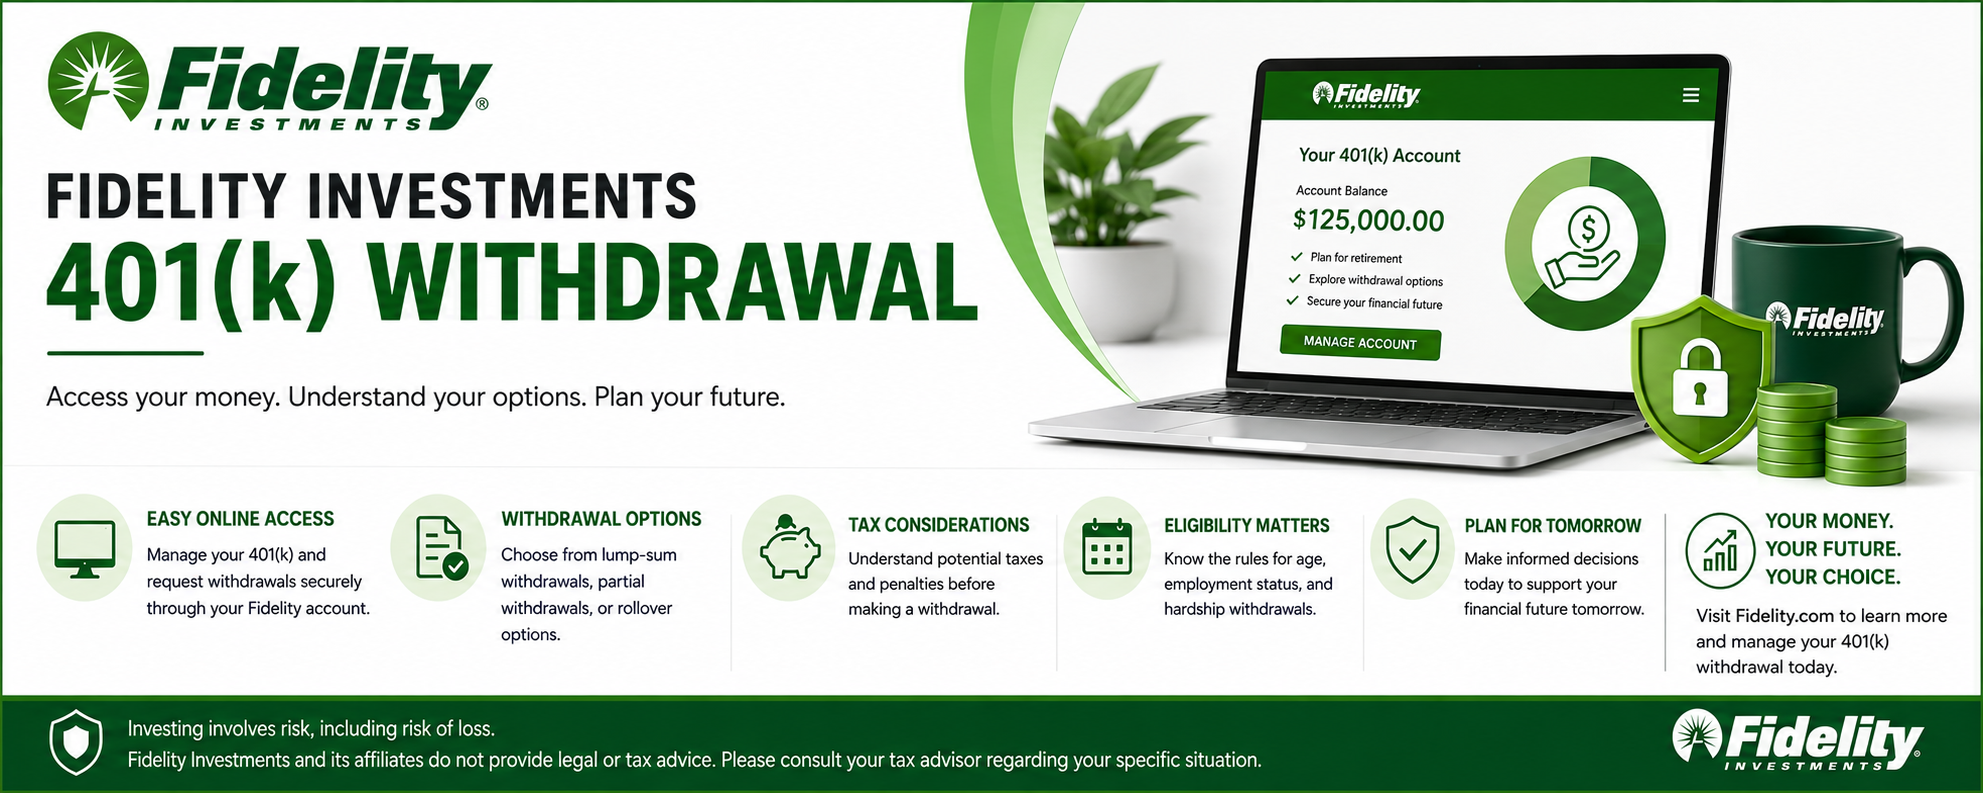
A Fidelity 401(k) withdrawal allows eligible participants to access money saved in an employer-sponsored retirement plan. These savings are generally intended to support retirement, but certain circumstances may allow participants to withdraw funds before retirement, take a plan loan, request a hardship distribution, or transfer their savings into another eligible retirement account. Understanding the available options can help us make informed decisions while protecting long-term retirement savings.
Fidelity Investments 401(k) withdrawal procedures depend on the specific retirement plan, the participant's employment status, age, account balance, and the distribution provisions established by the employer. Fidelity often administers workplace retirement plans, but the employer's plan document determines which withdrawal options are available. Therefore, two people with Fidelity-managed 401(k) accounts may have different withdrawal choices.
Before requesting a distribution, we should review the plan's rules, identify potential taxes and penalties, and compare withdrawals with alternatives such as loans or rollovers. A careful review can help us understand how accessing retirement funds today may affect our financial position in the future.
How to Withdraw Money from a Fidelity 401(k)?
The process for withdrawing money from a Fidelity 401(k) generally begins with reviewing the account and identifying the available distribution options. Participants can usually start by signing in to the official Fidelity website or contacting the plan administrator for assistance.
Step 1: Sign In to the Official Fidelity Website
We should access the official Fidelity website and sign in using the credentials associated with the workplace retirement account. After signing in, we can locate the retirement account and review its available features. The exact navigation and available options may vary according to the employer's plan.
For security, account holders should avoid sharing passwords, verification codes, or other sensitive information with unauthorized individuals.
Step 2: Review Available Withdrawal Options
The next step is to determine whether the plan permits a withdrawal while we are still employed or whether a qualifying event is required. Available options may include eligible in-service withdrawals, hardship distributions, plan loans, or distributions after leaving an employer.
We should carefully read the information displayed for each option. Some distributions may be restricted by age, employment status, the source of contributions, or specific plan provisions.
Step 3: Determine the Amount to Withdraw
Before submitting a request, we should calculate how much money is actually needed. Withdrawing only the required amount may help preserve the remaining retirement balance and reduce the potential tax impact.
It is also important to understand that the gross withdrawal amount may differ from the amount deposited into a bank account because of withholding, taxes, or other applicable deductions.
Step 4: Submit the Distribution Request
If the account is eligible, we can follow the plan's instructions to submit the withdrawal request. Depending on the plan, we may need to select a distribution method, confirm personal information, review tax withholding, and provide eligible payment details.
We should review the transaction carefully before submitting it and retain the confirmation for our records.
Step 5: Monitor the Request
After submitting the request, we can check the account for updates or contact the plan administrator if additional documentation is required. Processing times vary by distribution type, plan rules, verification requirements, and payment method. We should rely on the estimate provided for our specific transaction rather than assuming that every withdrawal will be completed within the same period.
Fidelity 401(k) Withdrawal Terms and Conditions
Understanding Fidelity 401(k) withdrawal terms and conditions is essential before accessing retirement funds. A plan may permit some distributions while restricting others, and the applicable rules depend on the participant's circumstances.
Important considerations include:
Employment status: Some plans permit certain withdrawals while an employee is still working, whereas others restrict access until employment ends or another qualifying event occurs.
Age requirements: Federal tax rules generally impose a 10% additional tax on taxable early distributions before age 59½ unless an exception applies.
Vesting rules: Employer contributions may be subject to a vesting schedule. The vested balance represents the portion the participant is entitled to retain under the plan's rules.
Tax treatment: Traditional 401(k) distributions are generally taxable as ordinary income, except to the extent that an exclusion or special tax treatment applies.
Plan-specific restrictions: The employer's plan document determines the permitted distribution types, minimum amounts, administrative procedures, and other conditions.
Payment methods: Depending on the plan, available methods may include electronic transfers, checks, or direct rollovers to another eligible retirement account.
Documentation: Certain transactions may require supporting documents, identity verification, or additional approvals.
We should confirm these conditions before initiating a transaction. Reviewing the plan's distribution information can prevent delays and help us avoid unexpected financial consequences.
Fidelity 401(k) Hardship Withdrawal: Eligibility and Requirements
A Fidelity 401(k) hardship withdrawal may allow an eligible employee to access retirement savings to meet an immediate and heavy financial need. However, hardship withdrawals are not automatically available under every plan, and the plan must permit the relevant distribution.
Qualifying needs under federal hardship distribution rules can include certain medical expenses, costs directly related to purchasing a principal residence, eligible tuition and educational expenses, payments necessary to prevent eviction or foreclosure, qualifying funeral expenses, certain expenses associated with repairing damage to a principal residence, and specified expenses or losses related to federally declared disasters.
The precise eligibility requirements depend on applicable law and the plan's provisions. Participants may need to certify that the distribution meets the relevant requirements and provide information requested by the plan administrator.
How a Hardship Withdrawal Works?
The process generally involves identifying an eligible financial need, reviewing the plan's hardship distribution policy, determining the permitted amount, and submitting the required request. The amount available may be limited by the plan and applicable rules.
A hardship distribution is generally not a loan. Once the money has been distributed, the participant ordinarily cannot repay it to the plan as though it were a loan. This means that the withdrawn amount may permanently reduce the retirement savings available for future use.
Hardship distributions from traditional 401(k) accounts are generally taxable, and an additional 10% early-distribution tax may apply if the participant is under age 59½ and no exception is available. A hardship withdrawal does not automatically qualify for an exemption from that additional tax.
Before proceeding, we should compare a hardship withdrawal with other available options, including a permitted plan loan, payment arrangements with creditors, or other sources of emergency funding.
Fidelity 401(k) Early Withdrawal: Taxes and Penalties
A Fidelity 401(k) early withdrawal generally refers to taking a distribution before reaching age 59½. Early access may be possible under the plan, but the tax consequences can be significant.
For a traditional 401(k), the taxable portion of a distribution is generally included in ordinary income for the year in which it is received. In addition, a 10% additional federal tax may apply to taxable distributions made before age 59½ unless a statutory exception applies.
For example, if we take a $10,000 taxable early distribution, the distribution may increase our taxable income by $10,000. If the full amount is subject to the 10% additional tax and no exception applies, the additional federal tax would be $1,000. Ordinary income taxes may also apply, and state tax treatment varies.
This example is for illustration only. Actual liability depends on the account's tax treatment, the participant's income, applicable deductions and credits, state law, and any available exceptions.
Common Exceptions to the 10% Additional Tax
Certain distributions may qualify for an exception to the additional 10% tax. For example, the federal rules generally provide an exception for distributions from an employer plan after separation from service during or after the calendar year in which the employee reaches age 55. Special rules apply to certain public safety employees and other circumstances.
Other exceptions may apply to qualifying disability, certain medical expenses, qualified domestic relations orders, and other situations specified by law.
Importantly, an exception to the 10% additional tax does not necessarily eliminate ordinary income tax. We should confirm the exact exception and its requirements before relying on it.
Fidelity 401(k) Cash Out After Leaving a Job
Leaving an employer may provide additional flexibility when deciding what to do with a Fidelity-managed 401(k). Depending on the plan, participants may be able to leave the money in the existing account, transfer it to a new employer's eligible plan, roll it into an IRA, or request a cash distribution.
Option 1: Leave the Money in the Existing Plan
If permitted by the plan and subject to any applicable balance requirements, we may leave our retirement savings in the former employer's plan. This option can allow the money to remain invested without creating an immediate taxable distribution.
We should review investment choices, administrative fees, account restrictions, and any applicable minimum balance requirements before deciding to leave the funds in place.
Option 2: Roll Over the Funds
A direct rollover can transfer eligible retirement funds to another qualifying retirement account without treating the transfer as a cash distribution to the participant. A rollover may be available to an eligible new employer's plan or an IRA, subject to the applicable rules and receiving account's requirements.
A direct rollover can help preserve the tax-deferred status of eligible traditional retirement savings. Roth accounts and other specialized balances may have different rollover rules.
Option 3: Cash Out the Account
A cash-out distribution provides access to eligible funds, but it can reduce retirement savings and create a tax liability. If the distribution is taxable, it is generally included in income for the applicable tax year. An additional early-distribution tax may also apply unless an exception is available.
We should calculate the estimated net amount after applicable withholding and potential taxes before choosing this option. Federal withholding is not necessarily the same as the final tax liability.
Fidelity 401(k) Loans and Withdrawals: What Is the Difference?
A Fidelity 401(k) loan and a withdrawal serve different purposes. A loan, when offered by the employer's plan, allows a participant to borrow from retirement savings and repay the amount under the plan's repayment schedule. A withdrawal permanently distributes money from the account, subject to the relevant rules.
Feature
401(k) loan
401(k) withdrawal
Availability
Only if the plan permits loans
Depends on plan rules and eligibility
Repayment
Generally required under the loan agreement
Generally cannot be repaid as a loan
Taxes
Usually not taxable if rules are followed
Tax may apply to the taxable portion
Early-distribution tax
Generally not applicable to a compliant loan
May apply to an early taxable distribution
Retirement savings
Loan balance is repaid under plan rules
Distributed amount leaves the account
Federal law generally limits plan loans to the lesser of $50,000 or 50% of the participant's vested account balance, subject to statutory exceptions and plan terms. Certain rules allow a different limit in specific circumstances.
Loan repayment generally occurs through payroll deductions, and the repayment period is commonly five years unless a longer period is permitted for a qualifying principal-residence loan. If employment ends or repayments stop, the outstanding loan may become subject to special tax rules. A loan offset or deemed distribution can create tax consequences, although certain eligible loan offsets may be rolled over within an applicable deadline.
We should compare the repayment obligations and employment-related risks of a loan with the tax consequences of a withdrawal before selecting either option.
Fidelity 401(k) Withdrawal Phone Number and Customer Support
Participants looking for a Fidelity 401(k) withdrawal phone number should obtain the correct contact details from an official source. The appropriate number may depend on the employer's retirement plan, the type of account, and the assistance required.
We can usually locate the plan's contact information by signing in to the official Fidelity website and checking the workplace retirement account's contact or help section. The latest plan statement and employer benefits department may also provide relevant details.
When contacting support, we should be prepared to explain whether we want to request a distribution, check a pending withdrawal, understand hardship eligibility, review loan options, or clarify tax withholding. Support representatives may explain the process and plan provisions, but they may not provide individualized tax or legal advice.
For account security, we should independently verify contact information through Fidelity's official website rather than relying on unsolicited calls, search advertisements, or messages requesting sensitive information.
How to Check Fidelity 401(k) Withdrawal Status?
After submitting a distribution request, we should monitor the account to determine whether the request is pending, approved, or completed. The status may depend on whether the plan requires additional verification, documentation, or administrative approval.
To check the status, we can:
1. Sign in to the official Fidelity account.
2. Open the workplace retirement plan.
3. Look for transaction history, distribution activity, or the relevant request status.
4. Review any messages requesting additional information.
5. Contact the plan administrator if the status remains unclear or the expected processing period has passed.
If a payment has been approved but has not arrived, we should confirm the payment method, processing date, and bank information through the official account. We should never share login credentials or verification codes with someone claiming to expedite a withdrawal.
Important Considerations before Withdrawing Retirement Funds
Before requesting a Fidelity 401(k) distribution, we should consider how the decision may affect our long-term financial stability.
Tax consequences: A taxable distribution can increase annual income and may affect our overall tax liability. We should consider federal income tax, potential state income tax, and any applicable additional tax.
Lost investment growth: Money withdrawn from a retirement account is no longer available to benefit from future investment returns within that account. The long-term impact depends on the amount withdrawn, investment performance, fees, and the time remaining until retirement.
Employer plan restrictions: Not every participant qualifies for every distribution option. We should verify eligibility with the plan administrator before making financial commitments based on an expected withdrawal.
Alternatives to cashing out: A plan loan, direct rollover, emergency savings, or payment arrangement may be worth evaluating, depending on our circumstances.
Professional guidance: A qualified tax professional or financial adviser can help us understand the potential consequences of a distribution and compare available alternatives.
Frequently Asked Questions
1. How do we withdraw money from a Fidelity 401(k)?
We can begin by signing in to the official Fidelity website and reviewing the distribution options available under our workplace retirement plan. If the plan permits the requested transaction and we meet the eligibility requirements, we can follow the instructions to submit the request.
2. Can we withdraw money from a Fidelity 401(k) while still employed?
Possibly. Some employer plans permit eligible in-service withdrawals, hardship distributions, or loans. Others restrict access while the participant remains employed. The available options depend on the plan document, applicable law, age, and the source of the funds.
3. What are the Fidelity 401(k) hardship withdrawal requirements?
A hardship distribution generally requires an eligible immediate and heavy financial need and must comply with the plan's provisions. Qualifying expenses may include certain medical costs, eligible education expenses, and payments necessary to prevent eviction or foreclosure. A hardship withdrawal may be taxable and may incur an additional early-distribution tax.
4. Can we cash out a Fidelity 401(k) after leaving a job?
In many cases, eligible participants can request a distribution after leaving their employer. However, cashing out may trigger income taxes and, depending on age and circumstances, an additional tax. Leaving the funds in the plan or completing an eligible rollover may be alternatives.
5. Is there a penalty for withdrawing a Fidelity 401(k) before age 59½?
A taxable early distribution is generally subject to a 10% additional federal tax unless an exception applies. Ordinary income tax may also apply. Certain distributions qualify for exceptions, so we should review the rules relevant to our circumstances.
6. What is the difference between a Fidelity 401(k) loan and a hardship withdrawal?
A 401(k) loan, if permitted, must generally be repaid according to the plan's terms. A hardship withdrawal is a distribution that ordinarily cannot be repaid as a loan. Loans and withdrawals have different eligibility requirements, repayment obligations, and potential tax consequences.
7. How can we find the Fidelity 401(k) withdrawal phone number?
We should check the official Fidelity website, sign in to the workplace retirement account, or consult our employer's benefits department. These sources can help us locate the correct contact information for our specific plan.
8. How long does a Fidelity 401(k) withdrawal take?
Processing times vary depending on the plan, transaction type, documentation, verification requirements, and payment method. We should review the estimate provided by the plan administrator and monitor the request for updates.
9. Can we roll over a Fidelity 401(k) instead of withdrawing the money?
Eligible funds may be transferred through a direct rollover to another eligible employer plan or an IRA. A properly completed direct rollover generally avoids current taxation on eligible traditional retirement funds, provided the transaction satisfies the applicable rules.